Meeting the Insurance Adjuster: What to Know
The adjuster's visit is usually the single most important appointment in a roof insurance claim. A little preparation makes a real difference in how accurate the resulting scope of loss turns out to be.
What an adjuster is actually doing on your roof
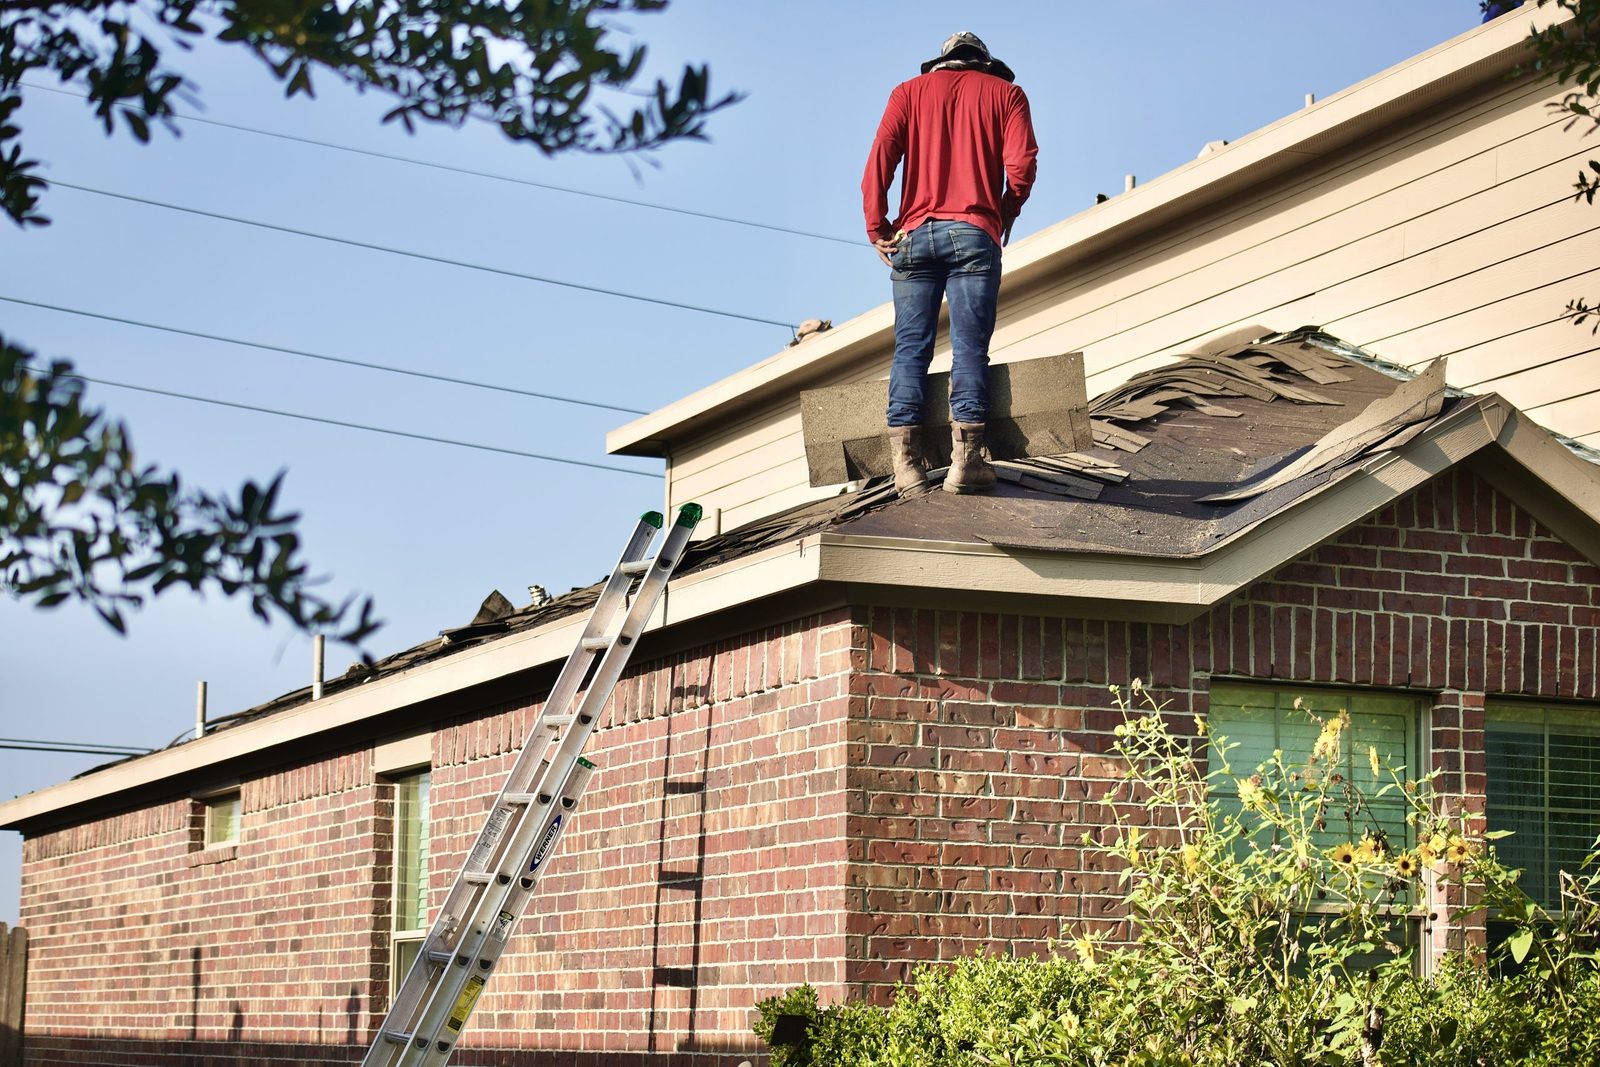
The adjuster is assessing the extent of damage tied to your claim and preparing a scope of loss — an itemized list of what the carrier will cover and at what cost. They're working from training and experience, but they're also typically covering many properties in a short window after a widespread storm, which means a thorough but efficient inspection is the norm rather than an exhaustive one.
Before the appointment
Have your own inspection report and photos ready, along with any notes about specific concerns — a leak, a stain, a particular area you're worried about. If you scheduled your own inspection ahead of the adjuster's visit, that documentation gives you a reference point to compare against what the adjuster ultimately reports.
Being present, or having your contractor present, matters
You don't have to attend, but being there, or having a contractor familiar with the roof present, means someone can point out damage the adjuster's initial pass might miss, particularly in hard-to-see areas. It also means you hear directly what the adjuster is noting, rather than learning about it only once the scope of loss arrives in writing.
If the resulting scope looks incomplete
It's common for a first estimate to miss something — decking damage under the shingles, a ventilation component, code-required upgrades. If that happens, a contractor can document the specific gap and submit a supplement, an additional request to the carrier. This is a routine, normal part of many claims and not something to be uncomfortable raising.
What happens after the visit
You'll receive the scope of loss and payout details from your carrier, typically structured around Replacement Cost Value or Actual Cash Value depending on your policy. Once you understand and accept the scope, or after any supplement is resolved, the roofing work itself can be scheduled.
Questions worth asking the adjuster directly
It's reasonable to ask the adjuster to walk through what they're finding as they go, rather than waiting for a written report days later. Ask specifically whether they checked ventilation components, flashing at every penetration, and gutters, not just the visible shingle surface. A clear, in-the-moment conversation on the roof often prevents confusion later when the written scope arrives.
Staying factual and specific throughout
The visit goes more smoothly when the conversation stays focused on what's actually visible and documented rather than speculation about cause or extent. If you have a specific concern — a room where you noticed a stain, a section of roof you're not sure about — say so directly and let the adjuster look rather than assuming they'll find it on their own.
What if the adjuster's visit gets rescheduled
After a widespread storm, adjuster appointments sometimes get pushed back simply due to volume, with many homes across the region needing inspections in a short window. If that happens, keep your own documentation current and mention any new developments, like an active leak that's started since your initial report, when the rescheduled visit does happen.
Keeping your own copy of everything
Even when a contractor is handling much of the documentation and communication with the adjuster, it's worth keeping your own copy of the inspection report, photos and any correspondence. It's your claim and your policy, and having independent records means you're never entirely dependent on someone else's file if a question comes up later, whether that's months from now or during a future claim on the same roof.
Frequently asked questions
Do I have to be present for the adjuster's visit?
It's not required, but being present, or having your contractor there, generally leads to a more accurate scope of loss.
What if the adjuster and my contractor disagree about the damage?
This happens occasionally and is usually resolved through documentation and, if needed, a supplement request rather than an argument on the roof itself.
Can I request a different adjuster or a re-inspection?
Yes, if you believe the initial inspection was incomplete, you can typically request a re-inspection through your carrier, supported by your own documentation.
Does the adjuster work for me or for the insurance company?
The adjuster represents your carrier's interests during the claim. That doesn't mean the process is adversarial, but it's part of why having your own documentation and, if helpful, a contractor present on your side of the conversation is worth doing.
Want the number before anyone visits?
Type your address and we'll measure the roof from aerial imagery — area, pitch and every facet — then price it at our published rate per square. About fifteen seconds, and we don't need your phone number to show you the number.
Storm damage?
Get help restoring your property after damage
Our technicians will give you a detailed damage inspection report, so you have everything your insurance company needs to make a decision.